Merger & Acquisition Advisory
When a PE firm signals interest or an LOI lands on the table, founders and CFOs want to close at the right valuation — and realize founder liquidity — without a last-minute DD finding or a tax structure mistake costing 20% of proceeds.
FAP
Registered CPAs
DFK
International Network
200+
Clients Served
24h
Response Time
What You Get
Full-Cycle M&A Support
Financial & Tax Due Diligence
Three to five years of financials reviewed for hidden liabilities, tax exposures, and earnings quality — integrated under one accountability chain, not split across two firms.
Defensible Valuation
DCF, comparable company, and precedent transaction analysis — a valuation range you can negotiate from, not guess from.
Tax-Efficient Deal Structure
Share purchase vs. asset transfer vs. Section 74 statutory merger — modelled with full Thai tax outcomes. The wrong structure surfaces 5–15% of deal value in unanticipated tax.
Post-Closing Integration
Financial consolidation, purchase accounting, and tax structure implementation — handled cleanly so integration starts on day one.
15+
Years of Experience
200+
Clients Served
CFO
Led Advisory
15+
Years of Experience
200+
Clients Served
CFO
Led Advisory
How It Works
Our Process
A clear, structured approach from start to finish.
Step 1: Transaction Strategy & Scoping
Define mandate (buy-side or sell-side), work-streams, and OTCC/SET regulatory obligations. OTCC timeline is assessed here — missing it mid-process is the most common cause of delayed Thai deal closings.
Step 2: Preliminary Assessment
Preliminary financial and operational analysis of the target. Preliminary EBITDA normalisation. Decision gate: proceed to full DD or not.
Step 3: Detailed Financial & Tax Due Diligence
Comprehensive review of 3–5 years of financial statements, tax returns (CIT/VAT/WHT/TP), related-party transactions, and contingent liabilities. Integrated under one working file.
Step 4: Valuation & Deal Pricing
Multi-methodology valuation range delivered to support negotiation — not a single number to defend, but a range you can negotiate from.
Step 5: Deal Structure & Negotiation
Share purchase vs. asset purchase vs. Section 74 statutory transfer based on Thai tax outcomes modelled for both parties. Key trade-offs committed to writing before structure is locked.
Step 6: Closing & Post-Closing Integration
Coordinate closing documentation, post-close accounting entries, and tax structure implementation. Transition support for finance-function integration.
Step 1: Transaction Strategy & Scoping
Define mandate (buy-side or sell-side), work-streams, and OTCC/SET regulatory obligations. OTCC timeline is assessed here — missing it mid-process is the most common cause of delayed Thai deal closings.
Step 2: Preliminary Assessment
Preliminary financial and operational analysis of the target. Preliminary EBITDA normalisation. Decision gate: proceed to full DD or not.
Step 3: Detailed Financial & Tax Due Diligence
Comprehensive review of 3–5 years of financial statements, tax returns (CIT/VAT/WHT/TP), related-party transactions, and contingent liabilities. Integrated under one working file.
Step 4: Valuation & Deal Pricing
Multi-methodology valuation range delivered to support negotiation — not a single number to defend, but a range you can negotiate from.
Step 5: Deal Structure & Negotiation
Share purchase vs. asset purchase vs. Section 74 statutory transfer based on Thai tax outcomes modelled for both parties. Key trade-offs committed to writing before structure is locked.
Step 6: Closing & Post-Closing Integration
Coordinate closing documentation, post-close accounting entries, and tax structure implementation. Transition support for finance-function integration.
Transparent Pricing
M&A Advisory — Bespoke Engagement Structure
M&A fees combine a fixed retainer with a success-fee component. Structure scopes by deal value, target complexity, and cross-border elements. Typical engagements run 3–9 months depending on complexity.
About our pricing:
| Tier / Variant | What's included | Timeline | Govt / 3rd-party fees | Plizz service fee |
|---|---|---|---|---|
| Standard — smaller asset purchases | Single-target Thai entity, THB 10–50M deal value, clean books, single-jurisdiction shareholders, no regulatory carve-outs. Scoping, financial / tax DD, valuation, deal coordination through closing. | 3–4 months | DBD registration (variable) + stamp duty 0.1% of share value + capital gains / CIT on disposal | Bespoke · retainer + success fee Reason for quote: Why: retainer + success fee % of deal value — deal-dependent structure |
| Mid-marketMost common | THB 100–500M deal value, financial + tax + light legal due diligence, OTCC notification considerations, single-jurisdiction with possible foreign component. | 4–6 months | DBD + newspaper publication (~500–1,500) + stamp duty 0.1% + capital gains / CIT | Bespoke · retainer + success fee Reason for quote: Why: retainer + success fee scales with deal value, DD scope, and cross-border elements |
| Complex — cross-border / regulated | Cross-border deal, multi-target / portfolio acquisition, regulated-industry target (financial services, healthcare, telecoms), OTCC pre-merger approval, Section 74 tax-neutral structuring, multi-jurisdiction tax planning. | 6–9 months | DBD + newspaper + stamp duty + capital gains tax + multi-jurisdiction tax | Bespoke · retainer + success fee Reason for quote: Why: cross-border + regulated industry + multi-jurisdiction tax = highest retainer + success-fee tier |
Standard — smaller asset purchases
Single-target Thai entity, THB 10–50M deal value, clean books, single-jurisdiction shareholders, no regulatory carve-outs. Scoping, financial / tax DD, valuation, deal coordination through closing.
- Timeline
- 3–4 months
- Govt / 3rd-party fees
- DBD registration (variable) + stamp duty 0.1% of share value + capital gains / CIT on disposal
- Plizz service fee
- Bespoke · retainer + success fee
Reason for quote: Why: retainer + success fee % of deal value — deal-dependent structure
Mid-market
THB 100–500M deal value, financial + tax + light legal due diligence, OTCC notification considerations, single-jurisdiction with possible foreign component.
- Timeline
- 4–6 months
- Govt / 3rd-party fees
- DBD + newspaper publication (~500–1,500) + stamp duty 0.1% + capital gains / CIT
- Plizz service fee
- Bespoke · retainer + success fee
Reason for quote: Why: retainer + success fee scales with deal value, DD scope, and cross-border elements
Complex — cross-border / regulated
Cross-border deal, multi-target / portfolio acquisition, regulated-industry target (financial services, healthcare, telecoms), OTCC pre-merger approval, Section 74 tax-neutral structuring, multi-jurisdiction tax planning.
- Timeline
- 6–9 months
- Govt / 3rd-party fees
- DBD + newspaper + stamp duty + capital gains tax + multi-jurisdiction tax
- Plizz service fee
- Bespoke · retainer + success fee
Reason for quote: Why: cross-border + regulated industry + multi-jurisdiction tax = highest retainer + success-fee tier
Optional Add-Ons
| Add-on | Fee | Notes |
|---|---|---|
| Part-time CFO support pre-/post-deal | Get a quote · 1 business day Reason for quote: Why: engagement intensity scopes with deal stage and post-merger integration depth | Especially valuable for sell-side preparation and post-merger integration. See Part-time CFO. |
| Tax advisory on transaction structure | Get a quote · 1 business day Reason for quote: Why: project scope depends on jurisdictions and structuring options | Critical for tax-efficient deal structuring. See Tax Advisory. |
| Legal due diligence | Quoted by corporate-law firm partner · Plizz coordinates Reason for quote: Why: coordinated with Plizz Group network; partner fee scales with deal complexity | Coordinated with Plizz Group's network of corporate-law firms. |
| Annual statutory audit (post-deal) | Quoted by CPA partner · Plizz coordinates Reason for quote: Why: CPA fee scales with post-deal revenue + transaction volume + subsidiaries | Often required by acquirers post-closing. See Annual Audit Compliance. |
Part-time CFO support pre-/post-deal
Reason for quote: Why: engagement intensity scopes with deal stage and post-merger integration depth
Especially valuable for sell-side preparation and post-merger integration. See Part-time CFO.
Tax advisory on transaction structure
Reason for quote: Why: project scope depends on jurisdictions and structuring options
Critical for tax-efficient deal structuring. See Tax Advisory.
Legal due diligence
Reason for quote: Why: coordinated with Plizz Group network; partner fee scales with deal complexity
Coordinated with Plizz Group's network of corporate-law firms.
Annual statutory audit (post-deal)
Reason for quote: Why: CPA fee scales with post-deal revenue + transaction volume + subsidiaries
Often required by acquirers post-closing. See Annual Audit Compliance.
Pricing Notes
- All Plizz fees exclude 7% VAT.
- Typical M&A engagements run 3–9 months depending on complexity. Fee structure typically combines a fixed retainer with a success-fee component.
- DFK International network: Plizz leverages its DFK membership for cross-border transactions across 100+ countries — useful for buy-side targets in or sell-side acquirers from outside Thailand.
- Government / 3rd-party fees (DBD, stamp duty 0.1%, capital gains / CIT on disposal gain) are pass-through; planned for in advisory.
Get a quote — typical response 1 business day
No commitment · Reply within 24 hours · Free initial consultation
Thai Regulatory Context
Why M&A in Thailand Has Unique Structural Risks
Three Thailand-specific factors materially determine M&A outcomes — and they are all deal-killers if discovered late.
Trade Competition Act B.E. 2560 — Suspensory Pre-Merger Approval
Under the Act, a transaction requires OTCC pre-merger approval where the combined entity would hold dominance — generally >50% market share, or top-three combined >75% with combined revenue exceeding THB 1 billion. This is a suspensory filing: the transaction cannot close until OTCC clears it. The OTCC has 90 days (extendable by 15) to decide. Post-merger notification is required within 7 days of closing for non-dominance deals above the revenue threshold. Discovering this mid-process is the most common cause of delayed Thai deal closings.
Revenue Code Section 74 Tax-Neutral Structuring Is Binary
Section 74 allows tax-neutral treatment of qualifying business transfers and reorganisations — deferring gain that would otherwise crystallise on transfer. Qualification requires: consideration consisting predominantly of shares (cash consideration generally disqualifies), continuity of business post-closing, and adherence to prescribed procedural conditions (registrar filings and creditor notification under CCC Sections 1238–1273). Failure on any one condition triggers full gain recognition in the year of transfer. Goodwill is generally not tax-deductible under Thai law — purchase-price allocation between goodwill and identifiable intangibles permanently drives the post-deal effective tax rate.
Loss Carry-Forward, Section 65 Ter, and BOT/SEC Cross-Border Layer
Under Section 65 Tri (12), net operating losses carry forward for up to 5 years. In a share purchase, losses survive (continuity of legal entity). In an asset purchase, they do not. For a target with material accumulated losses, the structure decision is made before signing, not after. Section 65 Ter explicitly disallows artificial expenses, fines, personal expenses, and unverifiable payments — items that routinely surface in DD and re-shape the offered price. For cross-border transactions, BOT FX regulations govern repatriation of proceeds, and the Securities and Exchange Act B.E. 2535 adds connected-party disclosure obligations for SET-listed parties.
Cascade consequence: SPA without pre-closing tax liability carve-out
An SPA that does not specifically carve out pre-closing tax liabilities means the buyer assumes them. The indemnification escrow shrinks. Founder net-proceeds fall 5–15%. This is not a theoretical risk — it surfaces in deals where financial and tax DD are rushed, split across separate firms, or deprioritised in the timeline. Plizz runs integrated financial + tax DD under one working file so no gap exists between what the financial DD found and what the tax DD covered.
Provider Comparison
Plizz vs. the Alternatives
Mid-market M&A buyers calibrate provider options before engaging. Here is the honest comparison.
| Dimension | Plizz | Big-4 Transaction Services | Investment-Bank Advisor | DIY (Founder-led) |
|---|---|---|---|---|
| Senior attention | Partner-led; founders have personally closed Thai-jurisdiction deals | Partner names the engagement; execution by managers and seniors | Banker leads; admin-heavy process | Founder manages, often learns after signing |
| Fee structure | Typically 30–50% of Big-4 fees for comparable mid-market deals; fixed retainer + success fee | Premium pricing sized to listed-company and large-cap deals | Success fee 2–5% of deal value — expensive for mid-market | Lowest upfront; highest risk-adjusted cost |
| Thai tax depth | Integrated financial + tax DD; Revenue Code + OTCC + BOT FX + SEC | Separate tax and financial streams; coordination gaps possible | Typically outsources tax DD | No structured tax DD |
| Cross-border | DFK International 100+ countries; Narai Partners IR Global for legal | Global network by design | Regional desk coverage | No network |
| Best for | THB 10M–1B+ mid-market; growth companies; founder exits | THB 1B+ listed-company transactions | Sell-side capital-markets processes | Transactions below THB 10M with known counterparties |
Who This Is For
Who Needs M&A Advisory?
M&A advisory is for mid-market buyers, sellers, and sponsors executing or preparing for a transaction where financial and tax complexity exceeds what an internal team can handle alone.
PE / VC funds executing roll-up acquisitions in Thailand
Buy-side financial and tax due diligence across multiple targets, normalised EBITDA reconstruction, Quality of Earnings analysis, and management-incentive structuring. DFK International network enables coordinated work when the fund holds assets in multiple countries.
Founders or shareholders preparing for a full or partial exit
Sell-side preparation, valuation defence, vendor due diligence pack, tax-efficient structuring of the disposal gain (15% WHT for individuals vs. CIT at 20% for corporate sellers), and earn-out negotiation. Sell-side prep typically runs 6–12 months ahead of target close.
Strategic buyers — MNE groups executing Thai add-on acquisitions
Local financial and tax DD, OTCC pre-merger filing assessment under the Trade Competition Act B.E. 2560, Section 74 structuring evaluation, BOI-privilege survivability analysis, and integration with global accounting and tax systems.
Family-office acquirers and distressed-asset buyers
Financial DD on targets with incomplete books, normalisation of earnings, and structuring of the acquisition vehicle to minimise post-deal tax drag.
Listed-company finance teams subject to SET disclosure
Connected-party transaction review, fairness opinion support, and disclosure obligation analysis under the Securities and Exchange Act B.E. 2535.
Not the right engagement if: the transaction is below ~THB 10M between known parties (existing accountant + corporate lawyer typically covers it), the "M&A" is an internal group restructuring with no third party (that is a restructuring engagement, scoped differently), or you are looking for someone to source acquisition targets (brokerage mandate, not advisory mandate).
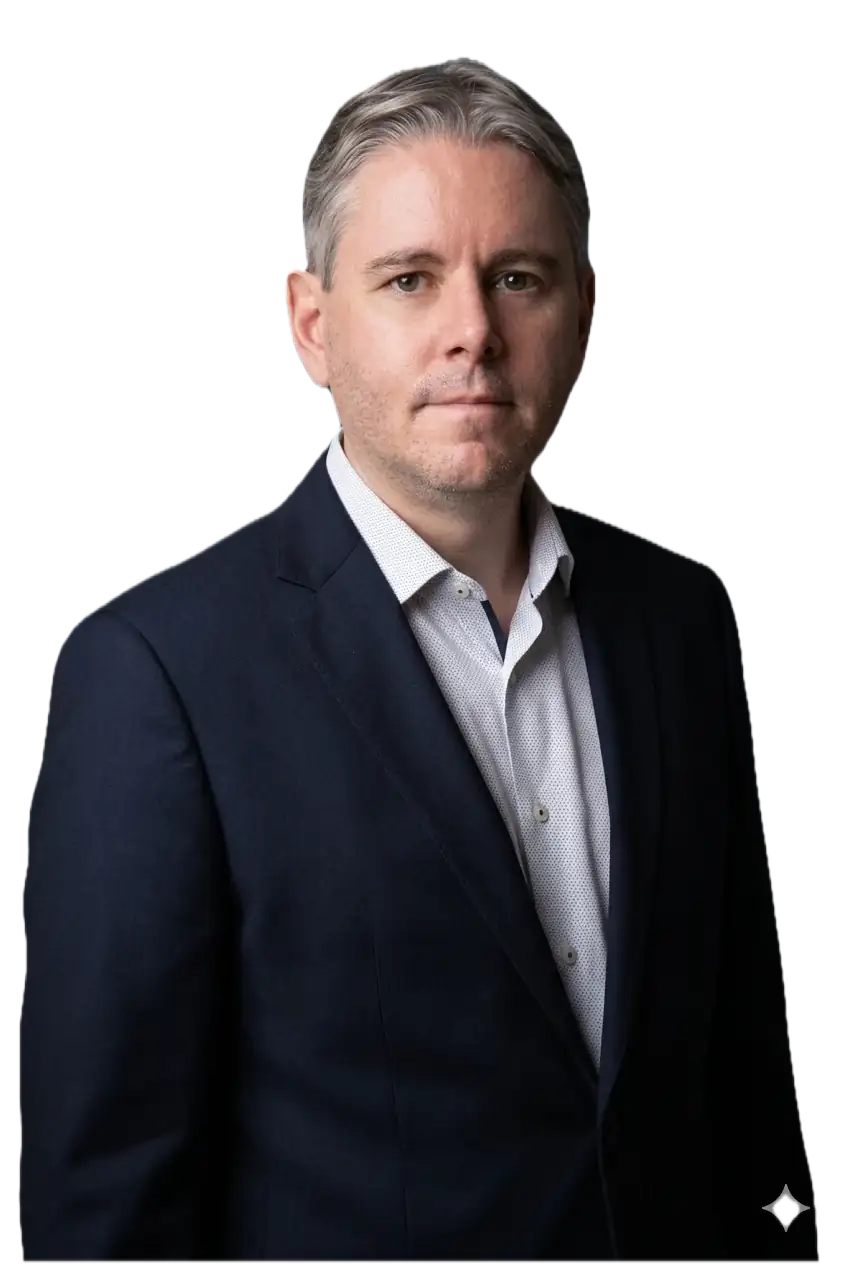
Your Plizz Contact
Benoît Meneau
CEO & CFO & Founding Partner
Corporate (re)structuring, cross-border transactions, international taxation, financial planning across SE Asia, MENA & Europe
Why Plizz
Why Choose Plizz for M&A Advisory
M&A advisory at Plizz is delivered by Plizz (Thailand) Co., Ltd., the Thailand member firm of DFK International — a global accounting and advisory network operating in 100+ countries. Founded in 2015 by two operating CFOs who have personally structured and closed transactions in the Thai market.
DFK
International Network
100+ Countries
IR Global
Narai Partners — Legal
Cross-Border Reach
Benoît
Meneau
CEO / CFO
Founding Partner
Jérôme
Le Louer
Co-Founding Partner
& CFO
Benoît Meneau & Jérôme Le Louer — founded by operating CFOs
Benoît Meneau (CEO/CFO/Founding Partner) held CFO roles at listed and private companies across SEA, South Asia, Middle East, and Africa — and has personally structured and closed Thai-jurisdiction transactions. Jérôme Le Louer (Co-Founding Partner & CFO) brings the same operating background. Advice is filtered through "we've sat in that seat," not "we've observed it from the outside."
30–50% of Big-4 fees for mid-market M&A
Comparable transaction-services work for deals in the THB 50M–1B range at a fraction of the Big-4 fee structure. Transparently quoted retainer + success fee before engagement begins. Walking away after DD is expected — the fee structure reflects that.
DFK International cross-border network
Coordinated financial and tax DD across 100+ countries. One accountability chain for buy-side targets outside Thailand and sell-side acquirers with foreign shareholders. Legal cross-border work coordinated through Narai Partners (IR Global member).
Integrated financial + tax DD under one firm
Financial and tax issues are intertwined. Revenue-recognition variances produce CIT exposures; related-party flows surface both TP and Section 65 Ter concerns. Splitting across firms creates coordination cost and analysis gaps. Plizz delivers both under one working file.
Common Questions
Frequently Asked Questions
Answers to the most common questions before and during engagement.
Explore More
Related Services
M&A advisory typically anchors a portfolio of pre-deal, deal, and post-deal engagements — tax structuring, investor-grade financials, and post-closing audit are engaged in parallel, not in sequence.
Tax Advisory
Section 74 tax-neutral structuring, transfer-pricing implications on post-deal intercompany flows, and post-closing tax integration — core to every deal. The advisory phase runs concurrently with M&A diligence, not after.
Part-Time CFO
Sell-side preparation (12 months of investor-grade financials and KPI infrastructure) and post-merger integration governance. CFO and M&A teams typically work in parallel during the deal-preparation window.
Annual Audit Compliance
Sell-side vendor DD packs and buyer's post-closing statutory audit — acquirers routinely require a clean audit of the target or combined entity within 6–12 months of closing. Pre-qualified as part of the Plizz engagement.
Bookkeeping
Clean books are a precondition for credible DD. Post-deal accounting integration — consolidation of acquired financials, purchase accounting entries — handled without onboarding a separate firm. From THB 9,900/month for Plizz Group clients.
BOI Promotion
Where the target holds BOI privileges that need to survive the transaction — or structuring around BOI is part of the deal logic — BOI analysis runs alongside deal structuring.
Get Started
Get a quote in 1 business day
Tell us the deal size, structure, and timeline — buy-side or sell-side. A senior partner reviews and quotes the engagement before you commit. No retainer until scope is agreed.
No credit card required · No commitment · Reply within 24 hours